How can you qualify for $25,000 less than you did two weeks ago?

Free Sweet Corn, Zucchinis & Cucumbers — Help Yourself!
September 17, 2026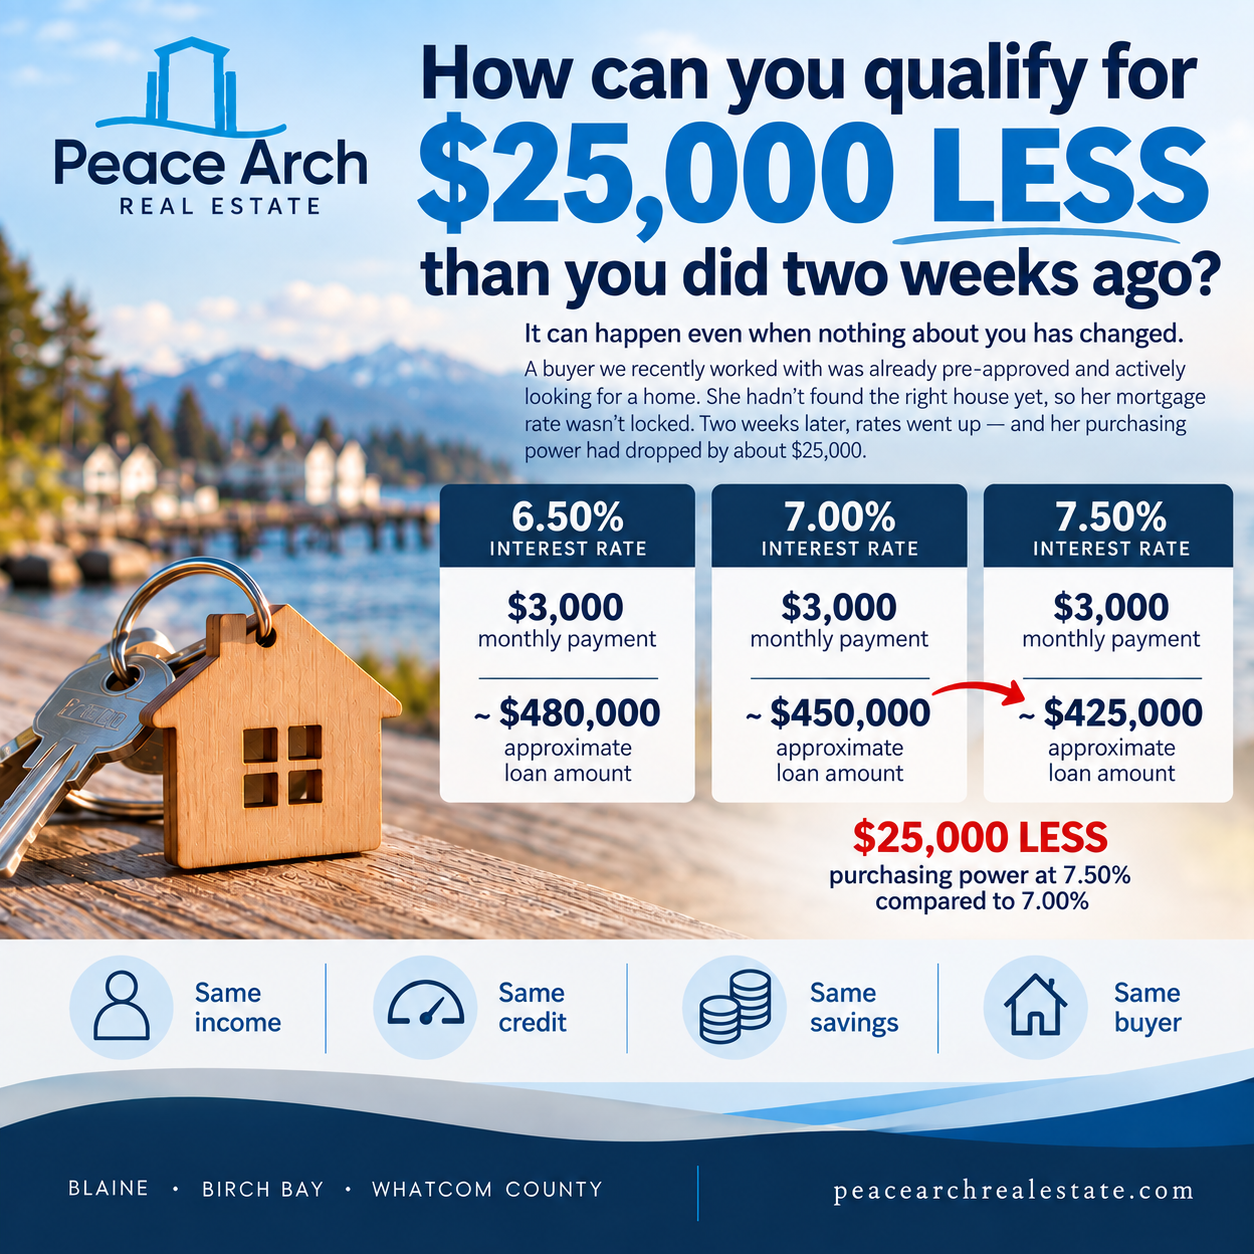
A buyer we recently worked with had already been pre-approved and was actively looking for a home. She knew approximately what she could afford, so we were searching within that price range.
Then mortgage rates went up.
She hadn’t found a home yet, so there was no property under contract and no mortgage rate to lock. When she checked back with her lender about two weeks later, she learned that her purchasing power had dropped by about $25,000.
Her income hadn’t changed. Her credit hadn’t changed. She hadn’t taken on new debt.
The interest rate had changed.
Why does a higher rate reduce what you can afford?
When a lender pre-approves you, the purchase price isn’t the only thing that matters. One of the most important factors is the monthly payment you can afford based on your income, debts and loan program.
That payment includes principal and interest, and usually property taxes and homeowners insurance. Depending on the property and loan, it can also include mortgage insurance and HOA dues.
When mortgage rates rise, the interest portion of the payment increases.
If the maximum monthly payment you qualify for stays roughly the same, something else has to give. Usually, that’s the amount you can borrow.
That means a buyer can have the same job, same income, same savings and same credit score and still qualify for a less expensive home than they did only a few weeks earlier.
A pre-approval isn’t a permanent number
This is something many buyers don’t realize.
Getting pre-approved is an important first step, but the amount on a pre-approval isn’t necessarily your purchasing power a month or even two weeks later.
Until you have a property under contract and work with your lender to lock your mortgage rate, market rates can continue to move.
Rates can go down and increase your purchasing power. They can also go up and reduce it.
That’s especially important when you’re shopping near the upper end of your approved price range. A relatively small change in rates can mean the house you could afford a few weeks ago may no longer fit within the lender’s guidelines today.
What should buyers do?
If you’re actively shopping for a home, stay in contact with your lender.
If rates have moved significantly since you were pre-approved, ask your lender to update your numbers before making an offer. You want to know your current purchasing power—not what it was several weeks or months ago.
And when comparing homes, think in terms of monthly cost, not just purchase price.
A pre-approval is a snapshot based on your finances and market conditions at that time. Until your rate is locked, that snapshot can change.
At Peace Arch Real Estate, part of our job is helping buyers understand not only which homes they can buy, but how financing, market conditions and the details of an individual property affect the real cost of buying one.
Peace Arch Real Estate
Blaine • Birch Bay • Whatcom County
peacearchrealestate.com
This information is for general educational purposes. Mortgage qualification and available rates vary by borrower, lender, loan program and property. Consult your mortgage professional for information specific to your situation.